Financial stress can affect anyone, but money worries may take on a different meaning later in life. During your working years, you may have had the opportunity to earn more money, work additional hours, or recover from a financial setback over time. In retirement, income is often more fixed, while expenses such as housing, healthcare, insurance, and everyday necessities can continue to change.
That can make an unexpected car repair, medical bill, increase in property taxes, or even a higher grocery bill feel more significant.
Fortunately, reducing financial stress doesn’t always require having substantially more money. Often, it begins with understanding exactly where you stand, simplifying your finances, preparing for unexpected expenses, and focusing on the financial decisions you can control.
Small changes can make your financial life easier to manage and give you greater confidence about the years ahead.
Understand Your Financial Picture Clearly
One of the first steps toward reducing financial stress is eliminating uncertainty.
It’s easy to feel anxious when you aren’t sure exactly how much money comes in each month, how much goes out, or how much you have available for emergencies.
Start by gathering your important financial information in one place.
This might include:
- Checking and savings account balances
- Social Security income
- Pension payments
- Retirement account balances
- Investment accounts
- Monthly household bills
- Insurance policies
- Credit card balances
- Mortgage information
- Auto or personal loans
- Regular medical and prescription expenses
You don’t need sophisticated financial software to do this. A notebook, simple spreadsheet, or basic budgeting application can work.
The goal is to answer three important questions:
How much money do I have coming in?
How much am I spending each month?
How much do I have available for unexpected expenses?
Once you know those numbers, financial decisions often become less intimidating.
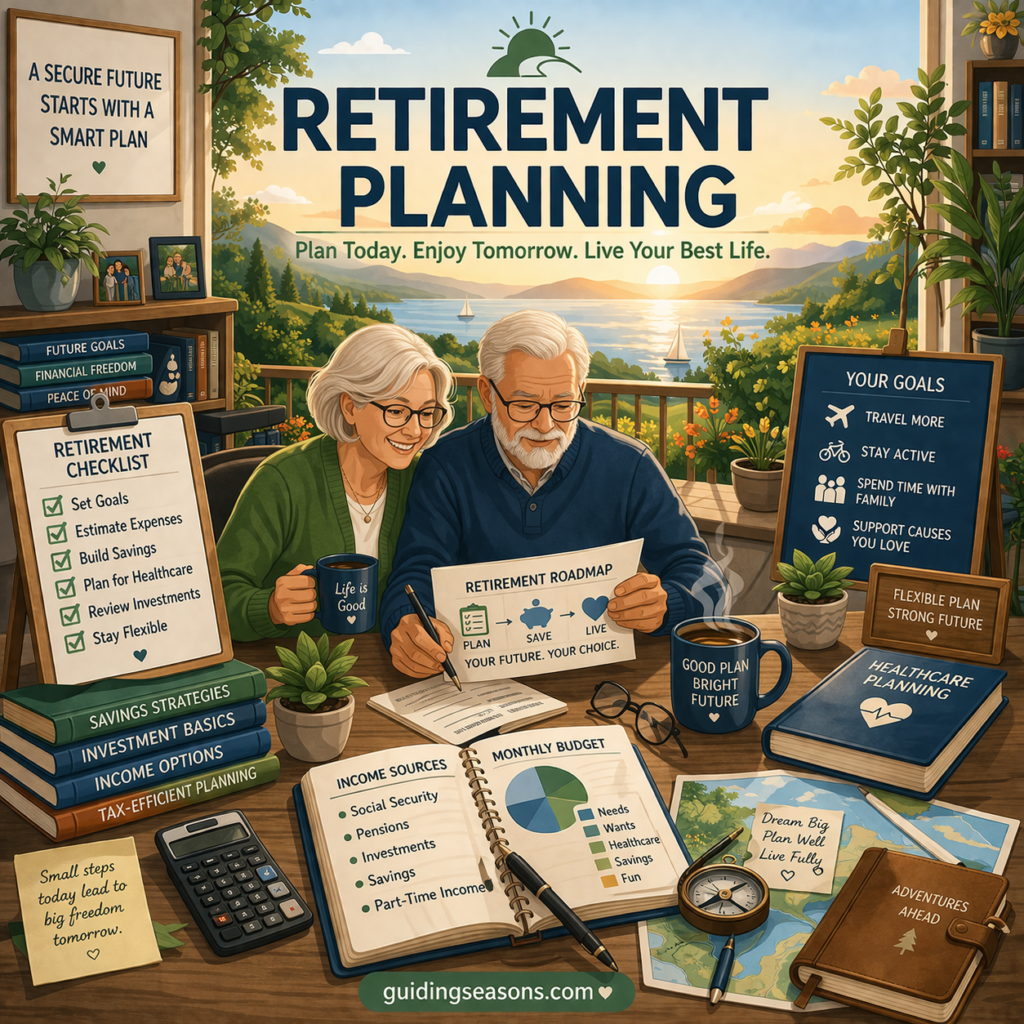
Create a Simple, Realistic Monthly Budget
A retirement budget doesn’t have to track every dollar you spend.
Instead, think of your budget as a basic roadmap showing where your income needs to go each month.
Start with dependable sources of income, such as:
- Social Security
- Pension income
- Retirement account withdrawals
- Annuity payments
- Part-time employment
- Rental or other regular income
Then list your regular expenses.
These might include:
- Housing
- Utilities
- Groceries
- Healthcare
- Prescription medications
- Insurance
- Transportation
- Debt payments
- Personal spending
- Entertainment
- Savings
Don’t make the budget unrealistically strict. If you enjoy eating at a restaurant twice a month or spending money on a hobby, include that expense.
A budget you can actually follow is more useful than a perfect budget that you abandon after two weeks.
A Simple Retirement Budget Example
Suppose a retiree receives $2,400 per month from Social Security and another $800 from a pension.
That’s $3,200 of monthly income.
If essential expenses total $2,350 and discretionary expenses average $450, approximately $400 remains each month.
Rather than simply allowing that $400 to disappear into miscellaneous purchases, the retiree could decide ahead of time to place $200 into emergency savings while keeping the other $200 available for irregular expenses.
Over one year, that $200 monthly contribution would add $2,400 to emergency savings.
That’s a relatively small monthly change that could make an unexpected home or automobile repair much less stressful.
Separate Essential Expenses From Optional Spending
One of the easiest ways to make your financial situation clearer is to divide expenses into two broad categories: needs and wants.
Essential expenses generally include:
- Housing
- Utilities
- Food
- Healthcare
- Insurance
- Basic transportation
- Required debt payments
Optional expenses may include:
- Restaurant meals
- Entertainment
- Vacations
- Subscription services
- Hobbies
- Gifts
- Nonessential shopping
This doesn’t mean you should eliminate everything enjoyable from your budget.
Retirement should still include activities that make life enjoyable.
The purpose of separating expenses is to understand how much money your household actually needs to operate each month.
If your essential expenses are comfortably below your reliable monthly income, you may discover that your financial position is stronger than you thought.
If essentials consume almost all of your income, you’ll know where to focus your planning efforts.
Look for Recurring Expenses You No Longer Need
Monthly subscriptions are convenient because the payments happen automatically. Unfortunately, that also makes them easy to forget.
Review your bank and credit card statements and look for recurring charges.
You may find:
- Streaming services you rarely watch
- Premium cable channels
- Memberships you no longer use
- Software subscriptions
- Magazine or newspaper subscriptions
- Cloud storage plans
- Expensive cellphone plans
- Duplicate services
Individually, these expenses may seem insignificant.
Together, they can become surprisingly expensive.
For example, eliminating three unused subscriptions costing $12, $15, and $18 per month would save $45 monthly.
That’s $540 per year.
Those savings could instead help pay for prescriptions, insurance deductibles, home maintenance, or emergency savings.
Automate Important Bills Carefully
Late payments can create unnecessary financial stress.
Automatic payments can make managing recurring expenses easier while reducing the possibility of forgetting a due date.
You might consider automating:
- Utility bills
- Insurance premiums
- Mortgage or rent payments
- Credit card minimum payments
- Regular savings contributions
However, automation doesn’t mean you should stop reviewing your accounts.
Check your bank and credit card statements regularly to make sure charges are correct and your account has enough money to cover upcoming automatic payments.
You can also set up account alerts for large purchases, low balances, or unusual activity.
Automation works best as a convenience—not as a replacement for monitoring your finances.
Build and Protect an Emergency Fund
Unexpected expenses are one of the biggest sources of financial anxiety.
The water heater breaks. Your car needs a major repair. You suddenly have an expensive dental procedure.
Without emergency savings, these expenses may end up on a credit card.
Having cash available can turn a financial crisis into an inconvenience.
If you don’t currently have much saved, don’t become discouraged by recommendations suggesting you immediately need thousands of dollars.
Start smaller.
Your first goals might be:
- $100
- $500
- $1,000
- One month of essential expenses
- Eventually, several months of expenses if your circumstances allow
Keep emergency savings somewhere safe and accessible, such as an FDIC-insured savings account.
The Federal Deposit Insurance Corporation explains that deposits at an FDIC-insured bank are automatically insured to at least $250,000 per depositor, per insured bank, for each account ownership category. You can learn more through the official FDIC deposit insurance guide.
An emergency fund isn’t designed to produce spectacular investment returns. Its primary purpose is to provide accessible money when something unexpected happens.
Reduce High-Interest Debt Where Possible
Debt can be especially stressful when you’re living primarily on retirement income.
Credit card debt deserves particular attention because high interest rates can make balances difficult to eliminate.
Suppose you have a $4,000 credit card balance charging 24% annual interest. At that rate, carrying the balance can become expensive very quickly.
Before accelerating debt payments, however, make sure you can still afford necessities and maintain some emergency savings.
Depending on your circumstances, strategies might include:
- Paying extra toward your highest-interest debt
- Paying off smaller balances to reduce the number of monthly bills
- Asking creditors whether lower-rate options are available
- Avoiding additional credit card debt when possible
Be cautious about debt consolidation products promising dramatically lower payments. A lower monthly payment isn’t necessarily a better deal if the repayment period becomes much longer or fees are added.
Review Insurance Regularly
Insurance protects against financial events that could otherwise severely affect your savings.
But insurance needs can change during retirement.
At least once a year, consider reviewing:
- Medicare coverage
- Medicare Advantage or Medigap coverage
- Prescription drug coverage
- Homeowners or renters insurance
- Automobile insurance
- Life insurance
- Long-term care coverage, if applicable
Ask whether you’re paying for overlapping or unnecessary coverage.
You can also ask your insurer about available discounts or whether changing your deductible could lower premiums.
Don’t reduce insurance solely to save money, though. Increasing a deductible from $500 to $2,000, for example, may lower your premium—but you need to be confident that you could afford the $2,000 expense if you actually had a claim.
Take Advantage of Programs Designed to Reduce Expenses
Older adults with limited income and resources may qualify for assistance programs they aren’t currently using.
Depending on eligibility, programs may help with:
- Medicare expenses
- Prescription drug costs
- Food
- Utilities
- Housing
- Property taxes
- Transportation
One useful starting point is the BenefitsCheckUp program from the National Council on Aging, which helps older adults identify potential benefit programs.
You can also use the federal government’s Benefits.gov successor resources at USA.gov to learn about government assistance programs.
Don’t assume your income automatically disqualifies you. Eligibility rules vary significantly among programs.
Simplify Your Financial Accounts
Over a lifetime, it’s common to accumulate multiple financial accounts.
You might have an old 401(k) from a previous employer, several bank accounts, multiple credit cards, and investment accounts at different institutions.
Keeping track of everything can become increasingly difficult.
Consolidating appropriate accounts may make your finances easier to understand and manage.
It can also make things easier for a trusted family member or representative if you eventually need assistance managing financial matters.
However, don’t move retirement accounts casually.
Rolling over or withdrawing money from retirement accounts can have tax and investment consequences. Consider consulting a qualified financial or tax professional before making significant changes.
Protect Yourself From Financial Scams
Reducing financial stress also means protecting the money you’ve already accumulated.
Older adults can be targeted by many types of fraud, including:
- Government impersonation scams
- Fake investment opportunities
- Tech-support scams
- Romance scams
- Lottery and sweepstakes scams
- Fraudulent charities
- Medicare-related scams
- Calls pretending to be relatives experiencing an emergency
One useful rule is simple:
Don’t make financial decisions under artificial pressure.
If someone unexpectedly calls, texts, or emails demanding immediate payment, threatening consequences, or insisting you keep the situation secret, stop communicating and independently verify the situation.
Never give passwords, verification codes, Social Security numbers, banking credentials, or Medicare information to an unsolicited caller.
If someone claims to represent a bank or government agency, contact the organization yourself using a trusted phone number or official website rather than the contact information provided by the caller.
Be Careful With Retirement Withdrawals
If you have retirement savings, deciding how much to withdraw can be just as important as deciding how the money is invested.
Taking too much early in retirement could increase the possibility of running short later. Taking too little might unnecessarily restrict your lifestyle.
Your appropriate withdrawal strategy depends on many factors, including:
- Age
- Account balances
- Social Security income
- Pension income
- Investment allocation
- Taxes
- Healthcare expenses
- Life expectancy
- Desired lifestyle
There is no withdrawal percentage that is perfect for everyone.
Consider creating an annual retirement income plan rather than withdrawing money whenever expenses arise.
Consider Professional Financial Guidance
If your financial situation feels difficult to manage, professional guidance may help.
A qualified financial professional can potentially help you:
- Organize retirement accounts
- Develop a spending plan
- Plan retirement withdrawals
- Evaluate investment risk
- Consider tax strategies
- Coordinate Social Security and retirement income
- Prepare for future healthcare expenses
- Review estate-planning considerations
Ask potential advisors how they’re compensated, what fees you’ll pay, what services are included, and whether they act as a fiduciary when providing advice to you.
You don’t necessarily need someone to manage every dollar you own. Sometimes paying for targeted advice about a specific retirement decision can be useful.
Prepare for Future Healthcare Costs
Healthcare deserves its own place in a retirement budget.
Medicare provides valuable coverage, but it doesn’t necessarily cover every healthcare expense.
Depending on your coverage and circumstances, you could still have expenses for:
- Premiums
- Deductibles
- Copayments
- Coinsurance
- Prescription drugs
- Dental care
- Vision care
- Hearing services
- Long-term care
Review your Medicare coverage annually and maintain room in your budget for healthcare expenses that aren’t completely predictable.
Planning for these costs can make them less disruptive when they occur.
Have Important Financial Documents Organized
Financial organization becomes increasingly important as you age.
Make sure important information can be located if you become ill or temporarily unable to handle your finances.
Depending on your circumstances, this could include:
- Bank and investment account information
- Insurance policies
- Property records
- Retirement account information
- Estate-planning documents
- Will or trust documents
- Powers of attorney
- Healthcare directives
- Contact information for financial professionals
Keep sensitive information secure, but make sure an appropriate trusted person knows how to access necessary documents in an emergency.
This isn’t just estate planning. It’s practical financial preparedness.
Don’t Let Money Anxiety Drive Every Decision
Financial stress isn’t purely mathematical.
Two people with identical incomes and savings can experience completely different levels of anxiety about money.
If you constantly check investment balances, worry about every purchase, or spend hours consuming alarming financial news, consider establishing boundaries.
For example, you might review your household budget once per week and investments once per month rather than checking them multiple times every day.
When financial anxiety appears, return to facts.
Instead of thinking, “What if everything goes wrong?” ask:
- What are my essential monthly expenses?
- How much reliable income do I receive?
- How much emergency savings do I have?
- What insurance protection do I have?
- What specific problem am I trying to solve?
Turning an undefined fear into a specific financial question often makes it easier to address.
Stay Connected With Other People
Money stress can become worse when you feel like you’re handling everything alone.
Maintaining relationships with family, friends, neighbors, and community organizations can provide both emotional and practical support.
Consider:
- Senior center activities
- Community organizations
- Volunteer opportunities
- Religious or civic groups
- Exercise or hobby classes
- Regular visits with friends and relatives
Trusted relationships can also provide another layer of protection against scams and impulsive financial decisions.
If an unexpected financial situation feels suspicious or confusing, having someone trustworthy to discuss it with can be extremely valuable.
Focus on What You Can Control
Inflation, interest rates, taxes, financial markets, and healthcare costs can change.
You can’t control all of them.
You can control many everyday decisions, including:
- How much you spend
- How much debt you carry
- Whether you maintain emergency savings
- How often you review insurance
- Whether you compare prices
- How carefully you protect yourself from fraud
- Whether you seek assistance when you need it
Focusing on controllable decisions can make financial problems feel more manageable.
Celebrate Financial Progress
Financial success in retirement doesn’t have to mean becoming wealthy.
Sometimes success means creating a stable life with the resources you already have.
Recognize meaningful accomplishments such as:
- Paying off a credit card
- Saving your first $500 emergency fund
- Canceling unnecessary subscriptions
- Following your budget for several months
- Reviewing your Medicare coverage
- Organizing financial documents
- Avoiding an unnecessary purchase
- Asking for professional help before making a major decision
Small financial improvements accumulate.
Saving $50 a month may not feel dramatic, but that’s $600 over a year. Finding another $75 in monthly savings increases the annual total by another $900.
Together, those two changes represent $1,500 per year that could remain available for other priorities.
Final Thoughts
Reducing financial stress later in life isn’t about creating a perfect financial situation. It’s about making your money easier to understand, easier to manage, and better prepared for unexpected events.
Start with the basics.
Know how much reliable income you receive. Understand your essential monthly expenses. Maintain emergency savings when possible. Reduce expensive debt. Review your insurance and Medicare coverage regularly. Simplify unnecessary accounts and subscriptions. Protect yourself from scams. And don’t hesitate to seek qualified assistance when a financial decision becomes too complicated to handle confidently on your own.
Most importantly, focus on progress rather than perfection.
Canceling one unnecessary subscription, saving your first $100, paying down a credit card balance, or simply organizing your financial paperwork may seem like small accomplishments. But each step gives you greater control over your financial life.
Retirement should not be dominated by constant worry about money. With organization, realistic planning, and consistent habits, you can reduce uncertainty and build a financial routine that supports greater confidence, stability, and peace of mind throughout your later years.
This article is for general educational purposes only and is not individualized financial, investment, tax, legal, or insurance advice. Consider consulting an appropriately qualified professional about decisions specific to your circumstances.