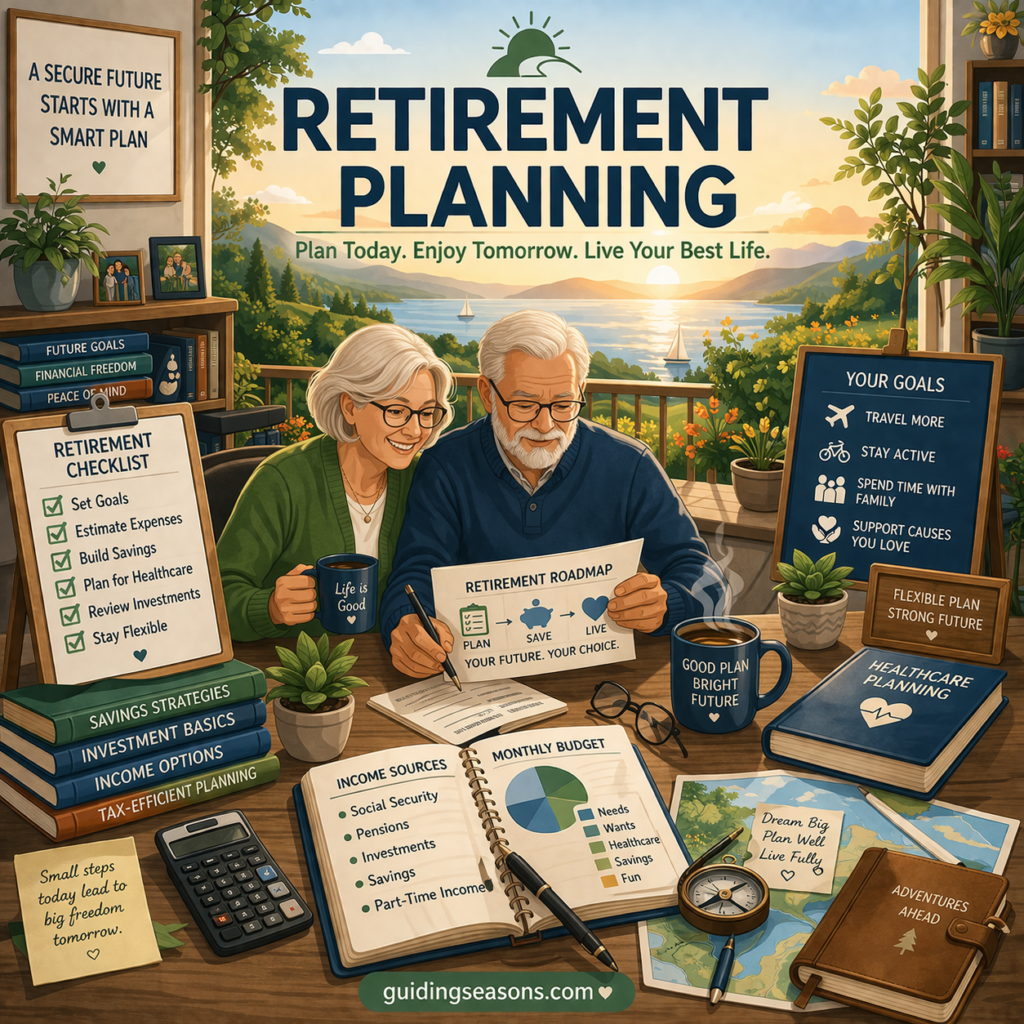
Retirement planning is one of the most important financial steps you can take, but it is also one of the easiest to postpone.
When retirement is still years away, other financial priorities can feel more urgent. Mortgages, everyday expenses, family responsibilities, debt, and unexpected costs often take precedence. Retirement can seem like something you will figure out later.
But retirement planning becomes more valuable when you give yourself time.
The goal isn’t simply to accumulate a certain amount of money. A strong retirement plan helps you understand how much you may need, where your income could come from, how your expenses might change, and how you will respond when life doesn’t go exactly according to plan.
Retirement also isn’t simply about stopping work. It’s about maintaining your lifestyle, protecting your independence, managing uncertainty, and creating a financial structure that can potentially support you for decades.
This guide walks through the major pieces of retirement planning and shows how they fit together.
What Retirement Planning Really Means
Retirement planning is the process of preparing your finances for a period when employment may no longer be your primary source of income.
A comprehensive retirement plan typically considers:
- Your expected retirement expenses
- Social Security and pension income
- Retirement savings and investments
- Healthcare expenses
- Taxes
- Inflation
- Required withdrawals from certain retirement accounts
- Emergency expenses
- Long-term care
- Your expected retirement timeline
- The possibility of living longer than anticipated
- Estate and important financial documents
These areas are interconnected.
For example, the amount you spend affects how quickly you withdraw from your savings. Withdrawals may affect your taxes. Healthcare expenses can change your budget, while inflation can gradually increase the cost of nearly everything you purchase.
That is why retirement planning works best as a complete system rather than a single savings goal.
Start by Understanding How Much Retirement May Cost
One of the first questions people ask is:
How much money will I need to retire?
There isn’t one number that works for everyone.
Your retirement income needs depend heavily on the lifestyle you expect to maintain.
Consider expenses such as:
- Housing
- Utilities
- Food
- Transportation
- Insurance
- Healthcare
- Taxes
- Travel
- Entertainment
- Hobbies
- Home maintenance
- Family support
- Unexpected expenses
Some expenses may decrease after you stop working, while others may increase.
Transportation and work-related costs, for example, could decline. Healthcare, travel, home maintenance, or assistance with daily activities could become more significant.
Instead of relying solely on a general percentage of your current income, build an estimate based on your expected lifestyle.
Read more: How to Estimate Your Retirement Income Needs
Build a Realistic Retirement Budget
Once you understand your likely expenses, turn those estimates into a retirement budget.
A useful budget separates expenses into several categories.
Essential expenses
These are expenses you will probably need to pay regardless of market conditions or lifestyle changes.
Examples include:
- Housing
- Utilities
- Groceries
- Insurance
- Basic transportation
- Healthcare
Flexible expenses
These are expenses you may be able to adjust when necessary.
Examples include:
- Travel
- Restaurants
- Entertainment
- Hobbies
- Gifts
- Recreational purchases
Irregular expenses
Some of the biggest retirement expenses don’t occur every month.
Examples might include:
- Home repairs
- Vehicle replacement
- Dental procedures
- Major medical expenses
- Family emergencies
Including these expenses makes your retirement budget much more realistic.
For a deeper look at creating a budget designed to last, see How to Build a Sustainable Retirement Budget.
You can also learn how to structure day-to-day spending in How to Build a Simple Retirement Spending Plan.
Understand Where Your Retirement Income Will Come From
Most retirees don’t rely on a single source of income.
Instead, retirement income may come from several places.
Common sources include:
- Social Security
- Employer pensions
- 401(k) accounts
- Traditional IRAs
- Roth accounts
- Personal savings
- Investment accounts
- Annuities
- Rental income
- Part-time work
Understanding how these income sources work together is one of the foundations of retirement planning.
For retirees with pensions, coordinating pension benefits with Social Security can be especially important.
Read: How to Combine Pensions and Social Security
Understand Your Social Security Options
Social Security may provide an important source of income throughout retirement.
One of the major decisions involves when to begin receiving benefits.
Your claiming decision can influence the amount of monthly income you receive, so it should be considered alongside your broader financial situation.
Factors that may influence the decision include:
- Your retirement age
- Other sources of income
- Your health and longevity expectations
- Whether you continue working
- Your household’s overall retirement strategy
Rather than viewing Social Security in isolation, consider how it fits into your complete income plan.
Read more: Understanding Social Security Options for Retirees
Strengthen Your Savings Before Retirement
The years leading up to retirement can provide an important opportunity to strengthen your financial position.
Depending on your circumstances, you might focus on:
- Increasing retirement contributions
- Reducing high-interest debt
- Building cash reserves
- Reviewing investment fees
- Consolidating unnecessary accounts
- Reconsidering major recurring expenses
Even relatively small improvements can accumulate over time.
The objective isn’t necessarily to make dramatic changes. It is to enter retirement with fewer financial weaknesses and a clearer picture of what you own and owe.
See How to Optimize Your Retirement Savings for additional strategies.
Create a Financial Safety Net
Retirement does not eliminate unexpected expenses.
A furnace can fail. A vehicle may need repairs. Dental work may be required. Family circumstances can change.
Without sufficient reserves, unexpected expenses may force you to withdraw more from retirement accounts than planned.
A financial safety net provides a buffer.
How large that buffer should be depends on your circumstances, but the principle is simple: not every unexpected expense should require selling investments or taking on debt.
Even retirees with limited income can work toward maintaining some emergency reserves.
Read: How to Build a Safety Net on a Fixed Income
Simplify Your Finances Before Retirement
Financial complexity can become increasingly frustrating as you get older.
Multiple bank accounts, old retirement accounts, unnecessary subscriptions, scattered investments, and complicated payment systems can make everyday money management harder than necessary.
Before retirement, consider whether your financial life can be simplified.
That might involve:
- Consolidating appropriate accounts
- Eliminating unused subscriptions
- Organizing automatic payments
- Creating a central list of financial accounts
- Reducing unnecessary recurring expenses
- Organizing important financial records
A simpler system can make budgeting, taxes, withdrawals, and financial decision-making easier.
See How to Simplify Your Finances Before Retirement.
Plan for Healthcare Before You Retire
Healthcare deserves its own place in your retirement plan.
Your healthcare expenses can include more than insurance premiums.
You may also face:
- Deductibles
- Copayments
- Prescription costs
- Dental care
- Vision care
- Hearing care
- Medical equipment
- Services not fully covered by insurance
Understanding your coverage and estimating potential out-of-pocket costs can help prevent healthcare expenses from disrupting your retirement budget.
For people approaching Medicare eligibility, learning how Medicare works before enrollment can make the transition easier.
Read: Understanding Medicare Options in Retirement
Don’t Ignore Long-Term Care
Long-term care is different from ordinary healthcare.
It can include assistance with everyday activities because of aging, disability, or chronic health needs.
Care could potentially be provided:
- At home
- Through community services
- In assisted living
- In a nursing facility
- Through family caregivers
Not everyone will require the same level of care, but the potential expense makes long-term care an important part of retirement planning.
Planning can involve thinking about your preferences, available resources, insurance options, family support, and how care expenses would affect your finances.
Read the full guide: How to Plan for Long-Term Care Expenses
Understand Taxes in Retirement
Retirement doesn’t necessarily mean the end of income taxes.
Different income sources can receive different tax treatment.
Depending on your circumstances, taxable retirement income might include distributions from certain retirement accounts, pension income, investment income, wages, and potentially a portion of Social Security benefits.
Taxes can also affect how much money you actually have available to spend.
That makes tax planning an important part of estimating retirement income.
Instead of focusing only on gross income, think about the amount you may have available after taxes and other expenses.
Learn more: How to Manage Taxes During Retirement
Understand Required Minimum Distributions
Certain retirement accounts may eventually require you to begin taking distributions under federal tax rules.
These withdrawals are commonly known as required minimum distributions, or RMDs.
RMDs matter because they can affect:
- Taxable income
- Withdrawal planning
- Account balances
- Cash flow
- Other parts of your retirement strategy
Understanding the rules before required withdrawals begin gives you more time to plan.
Read: Understanding Required Minimum Distributions
Because tax and retirement-account rules can change, verify current requirements with official sources or an appropriate tax or financial professional before making decisions.
Create a Long-Term Withdrawal Strategy
Accumulating retirement savings is only half of retirement planning.
Eventually, you need a strategy for using that money.
The challenge is balancing two competing needs:
You need enough income to enjoy retirement today, while preserving enough resources for the future.
Your withdrawal strategy may need to consider:
- Your annual spending
- Social Security and pension income
- Account types
- Taxes
- Investment performance
- Inflation
- Healthcare expenses
- Longevity
Your withdrawal amount doesn’t necessarily have to remain identical every year.
A flexible strategy can allow spending to adjust as your needs and financial circumstances change.
Explore this topic further in Creating a Long-Term Withdrawal Strategy.
Continue Managing Investments After Retirement
Retirement doesn’t automatically mean your investment planning stops.
If your retirement could last several decades, part of your savings may still need to support future spending many years from now.
At the same time, taking excessive investment risk can expose money needed for near-term expenses to significant volatility.
The appropriate balance depends on factors such as:
- Your income needs
- Your time horizon
- Other guaranteed or predictable income
- Your tolerance for market fluctuations
- Your overall financial situation
The objective is not simply to maximize returns. It is to build an investment approach that supports your retirement plan.
Read: How to Manage Investments After Retirement
Balance Growth With Financial Safety
A retirement portfolio often has to accomplish more than one goal.
Some assets may be intended for near-term spending, while others may need to remain invested for many years.
Keeping everything in very conservative assets may reduce short-term volatility but can introduce other challenges. Taking too much investment risk can expose retirement savings to losses at inconvenient times.
Finding an appropriate middle ground is therefore an important retirement decision.
Learn more: How to Balance Risk and Safety in Retirement
Protect Your Purchasing Power From Inflation
Inflation can quietly affect retirement plans.
Imagine that your lifestyle initially costs $50,000 per year.
If the prices of housing, food, healthcare, insurance, utilities, and other expenses rise over time, maintaining that same lifestyle may eventually require considerably more income.
That is particularly important for someone who spends 20, 30, or more years in retirement.
Your retirement plan should therefore account for the possibility that expenses will increase rather than remain fixed.
See How to Protect Your Retirement From Inflation.
Prepare for a Longer Retirement
Living longer is generally positive, but longevity creates an important financial challenge.
Your money may need to support you longer than expected.
A longer retirement can mean additional years of:
- Housing costs
- Food
- Healthcare
- Insurance
- Taxes
- Transportation
- Personal expenses
- Long-term care
Planning only for an average life expectancy can leave little margin if you live significantly longer.
A more resilient strategy considers what would happen if retirement lasts longer than anticipated.
Read: How to Prepare for Longevity and Future Needs
Adjust Your Budget as Retirement Changes
Your retirement budget shouldn’t necessarily remain unchanged for decades.
Spending patterns can evolve.
Early retirement may include more:
- Travel
- Entertainment
- Hobbies
- Home projects
- Social activities
Later retirement may involve less travel but potentially higher healthcare or support expenses.
Inflation can also change the amount required for everyday necessities.
Reviewing your budget periodically allows your plan to respond to your actual life rather than assumptions you made years earlier.
See How to Adjust Your Budget During Retirement.
Preparing for Early Retirement Requires Additional Planning
Retiring before the traditional retirement age can be appealing, but it creates additional financial considerations.
An early retirement may mean:
- More years without employment income
- More years of withdrawals
- Healthcare expenses before Medicare eligibility
- Different Social Security timing decisions
- A longer overall retirement period
Even a difference of several years can substantially change the length of time your savings need to support you.
If early retirement is part of your goal, build a plan specifically around that timeline rather than simply moving a traditional retirement plan forward.
Read: How to Prepare for Early Retirement
Prepare Your Important Documents
Retirement planning isn’t only about savings and investments.
Organization matters too.
Important documents and information may include:
- Estate planning documents
- Beneficiary information
- Insurance policies
- Property records
- Retirement account information
- Tax records
- Healthcare documents
- Lists of financial accounts
- Important contact information
Keeping these documents organized can make financial management easier for you and potentially for trusted family members or representatives who may need to help in the future.
See Essential Documents to Prepare Before Retiring.
Avoid Common Retirement Planning Mistakes
Even people who save consistently can make mistakes that weaken their retirement plan.
Common problems include:
- Waiting too long to plan
- Underestimating expenses
- Ignoring inflation
- Forgetting about taxes
- Underestimating healthcare expenses
- Depending too heavily on one income source
- Taking too much or too little investment risk
- Withdrawing too aggressively
- Failing to maintain emergency reserves
- Never updating the plan
Perhaps the biggest mistake is treating retirement planning as a one-time event.
Retirement planning is an ongoing process.
Your income, health, expenses, markets, tax rules, family circumstances, and goals can change.
Review your plan periodically and adjust when necessary.
For a deeper discussion, read Mistakes to Avoid When Planning Retirement.
How to Reduce Financial Stress in Retirement
Financial security isn’t only about maximizing the amount of money you accumulate.
Simplicity and predictability matter too.
Financial stress can sometimes be reduced by:
- Maintaining an emergency reserve
- Keeping debt manageable
- Understanding your monthly expenses
- Automating routine bills
- Organizing accounts and documents
- Maintaining several income sources
- Having a plan for unexpected expenses
Knowing what you will do when circumstances change can make uncertainty easier to manage.
Read: How to Reduce Financial Stress Later in Life
Build a Plan Designed to Last for Decades
A successful retirement plan needs to work beyond the first few years after leaving the workforce.
That means thinking long term.
Ask yourself:
- What happens if I live longer than expected?
- What if inflation remains elevated for a period?
- What if investment markets decline?
- What if healthcare costs increase?
- What if my housing situation changes?
- What if I need help with daily living?
- What expenses could I reduce if necessary?
You cannot predict every scenario.
You can, however, build enough flexibility into your plan that unexpected events don’t automatically become financial emergencies.
For more, see How to Ensure Financial Stability for Decades.
A Simple Retirement Planning Checklist
Retirement planning becomes easier when you break it into manageable steps.
Before retirement, consider working through the following:
- Estimate your retirement expenses.
- Calculate expected Social Security and pension income.
- Review your retirement savings and investments.
- Create a realistic retirement budget.
- Build or maintain an emergency reserve.
- Review your debt.
- Understand your healthcare coverage.
- Consider potential long-term care needs.
- Review the tax treatment of your income sources.
- Create a withdrawal strategy.
- Review your investment risk.
- Account for inflation and longevity.
- Organize important documents.
- Review beneficiary information.
- Revisit your retirement plan regularly.
You don’t have to complete everything at once.
Each step improves your understanding of your financial position.
Your Retirement Plan Should Change With You
One of the most important principles of retirement planning is flexibility.
The plan you create at age 50 may not be the plan you need at 60.
And the plan you begin retirement with may look different ten years later.
Life changes.
So can:
- Your health
- Your spending
- Your family situation
- Your housing
- Your investments
- Tax rules
- Government benefits
- Your priorities
Instead of trying to predict everything perfectly, create a retirement plan capable of adapting.
That flexibility can be just as important as the original plan.
Continue Building Your Retirement Plan
Retirement planning covers many areas, and you don’t need to understand everything at once.
Use these guides to explore individual parts of your plan in greater detail:
- How to Estimate Your Retirement Income Needs
- Understanding Social Security Options for Retirees
- How to Build a Sustainable Retirement Budget
- How to Optimize Your Retirement Savings
- Creating a Long-Term Withdrawal Strategy
- Understanding Medicare Options in Retirement
- How to Plan for Long-Term Care Expenses
- How to Manage Taxes During Retirement
- How to Protect Your Retirement From Inflation
- How to Prepare for Longevity and Future Needs
Final Thoughts
Retirement planning isn’t about predicting exactly what your life will look like decades from now.
It’s about creating enough financial structure and flexibility to handle whatever those decades bring.
Start with the fundamentals:
- Understand what retirement may cost.
- Identify where your income will come from.
- Build and protect your savings.
- Prepare for healthcare and long-term needs.
- Develop a sustainable spending and withdrawal strategy.
- Keep your finances organized.
- Review your plan as your circumstances change.
You don’t need a perfect retirement plan today.
You need a plan that is realistic, understandable, and capable of changing with you.
Taking those steps gradually can help turn retirement from an uncertain financial milestone into a future you are better prepared to manage.