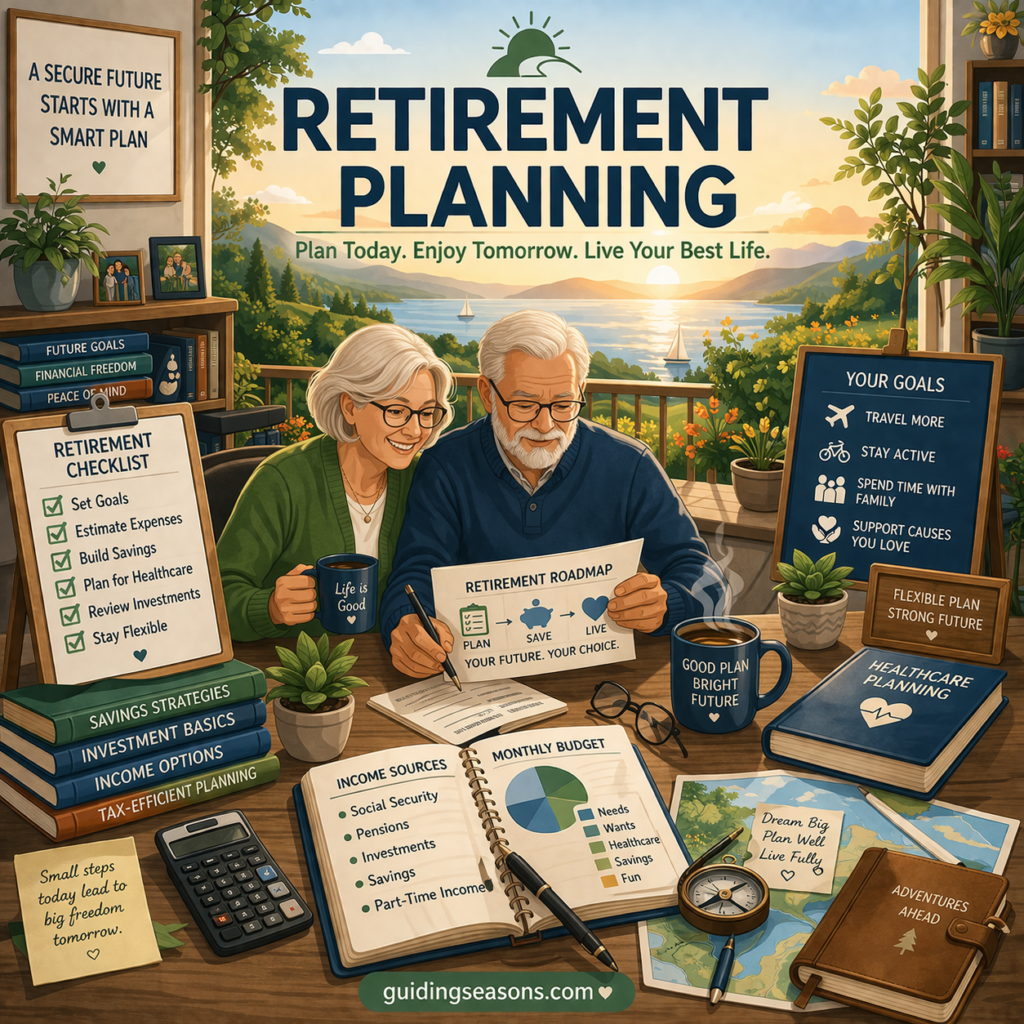
A retirement budget isn’t just about numbers—it’s about creating peace of mind.
After decades of working, earning, saving, and paying bills, retirement changes the way money flows through your life. Instead of receiving a regular paycheck from an employer, your income may come from several different sources, including Social Security, pensions, retirement accounts, investments, annuities, or part-time work.
At the same time, your expenses don’t disappear. Housing, groceries, insurance, transportation, healthcare, entertainment, travel, and unexpected costs still need to be covered.
That’s why building a sustainable retirement budget is so important.
The goal isn’t to restrict every purchase or worry about every dollar. A good retirement budget helps answer a much more useful question:
How can I comfortably enjoy my money today while protecting my financial security for the future?
The answer will be different for everyone, but a few basic principles can help you build a budget that is realistic, flexible, and easier to maintain.
Why Retirement Budgeting Feels Different
Budgeting during retirement can feel very different from budgeting during your working years.
While working, you generally know another paycheck is coming. If an unexpected expense appears, you may be able to work overtime, postpone retirement contributions, or earn additional income.
Retirement changes that equation.
Income may be more limited, while your savings may need to last for decades. In fact, the Consumer Financial Protection Bureau (CFPB) notes that people may spend 20 years or more in retirement, making long-term financial planning especially important.
That can create understandable concerns about:
- Outliving retirement savings
- Unexpected healthcare expenses
- Inflation
- Home repairs
- Helping children or grandchildren
- Market downturns
- Long-term care
- Losing a spouse or partner
- Maintaining a desired lifestyle
A sustainable budget can’t eliminate every uncertainty.
What it can do is help you prepare for uncertainty without allowing it to dominate your retirement.
Start by Understanding Your Retirement Income
Before deciding how much you can spend, determine how much income you can reasonably expect.
Write down each source of retirement income.
That might include:
- Social Security
- Pension payments
- Retirement account withdrawals
- Annuity payments
- Investment income
- Rental income
- Part-time employment
- Other reliable sources
Separate guaranteed or relatively predictable income from income that may fluctuate.
For example, Social Security and a traditional pension may provide predictable monthly payments, while withdrawals from an investment portfolio depend partly on your savings, investment strategy, and market conditions.
Social Security deserves particular attention. The CFPB points out that the age at which you claim benefits affects your monthly payment. For people born in 1960 or later, claiming before full retirement age can result in a substantially smaller monthly benefit, while delaying benefits beyond full retirement age can increase the monthly amount up to age 70.
Decisions about Social Security should therefore be considered as part of your overall retirement budget rather than in isolation.
Separate Essential Expenses From Lifestyle Expenses
Once you understand your income, look at your spending.
A useful approach is dividing expenses into two broad categories.
Essential expenses
These are expenses necessary to maintain your basic lifestyle.
They may include:
- Mortgage or rent
- Property taxes
- Homeowners or renters insurance
- Utilities
- Groceries
- Healthcare
- Prescription medications
- Transportation
- Auto insurance
- Basic household expenses
- Minimum debt payments
Lifestyle and discretionary expenses
These expenses aren’t necessarily required for survival, but they contribute greatly to quality of life.
They might include:
- Restaurants
- Travel
- Hobbies
- Entertainment
- Gifts
- Streaming services
- Club memberships
- Family activities
- Personal shopping
Don’t make the mistake of eliminating enjoyable spending simply because it isn’t “essential.”
Retirement is supposed to include enjoyment.
Instead, understand which expenses you could adjust temporarily if your financial circumstances changed.
That distinction creates flexibility.
Try a Three-Bucket Retirement Budget
Another simple way to organize retirement spending is to divide expenses into three categories:
Needs: Housing, food, utilities, healthcare, transportation, and insurance.
Wants: Restaurants, entertainment, hobbies, travel, gifts, and other enjoyable activities.
Future and unexpected expenses: Emergency savings, major home repairs, replacement vehicles, healthcare surprises, and other irregular costs.
This doesn’t require following a rigid percentage.
Your housing and healthcare expenses might naturally consume more of your budget than someone else’s.
The purpose is simply to make sure you’re considering all three categories.
What a Retirement Budget Might Look Like
Consider a hypothetical retiree named Robert.
Robert receives:
- $2,400 per month from Social Security
- $900 per month from a pension
- $1,000 per month from planned retirement-account withdrawals
His available monthly income is approximately $4,300 before considering taxes and other individual factors.
Suppose his monthly spending looks like this:
- Housing, taxes, and insurance: $1,300
- Utilities and communication: $300
- Food: $600
- Healthcare: $500
- Transportation: $350
- Entertainment and hobbies: $300
- Travel fund: $250
- Miscellaneous spending: $250
- Emergency/irregular expense fund: $250
Total planned spending: $4,100 per month.
That leaves approximately $200 of monthly breathing room.
More importantly, Robert knows which expenses are flexible.
If he suddenly needs a $1,500 home repair, he may temporarily reduce travel and entertainment spending rather than feeling that his entire retirement plan has failed.
That’s what makes a budget sustainable.
It provides structure without requiring perfection.
Don’t Forget Irregular Expenses
One of the biggest mistakes in retirement budgeting is focusing exclusively on monthly bills.
Many major expenses don’t arrive every month.
Think about:
- Property taxes
- Car registration
- Dental work
- Home repairs
- Appliance replacement
- Holiday gifts
- Vacations
- Insurance premiums
- Vehicle maintenance
- Pet care
- Family celebrations
A $2,400 annual expense doesn’t feel like a monthly expense—but financially, it is.
Divide it by 12 and set aside $200 per month.
Creating small monthly reserves for predictable annual expenses can make large bills much easier to manage.
Prepare for Healthcare Expenses
Healthcare deserves its own section in almost every retirement budget.
Even with Medicare or other insurance, retirees may still face premiums, deductibles, copayments, prescriptions, dental care, vision care, hearing services, and other out-of-pocket expenses.
Healthcare expenses can also change considerably over a long retirement.
Rather than trying to predict exactly what you’ll spend 15 years from now, build flexibility into your budget.
Consider:
- Current insurance premiums
- Regular prescriptions
- Dental and vision expenses
- Copayments and deductibles
- Potential increases in premiums
- Emergency medical expenses
- Possible long-term care needs
Reviewing these costs annually can help prevent healthcare expenses from becoming an unpleasant surprise.
Build an Emergency Buffer
Retirement doesn’t eliminate emergencies.
Water heaters still break. Cars need repairs. Roofs eventually need replacement. Dental emergencies happen.
That’s why a sustainable retirement budget should include money for unexpected expenses.
The appropriate amount depends on your circumstances.
Someone who owns an older home and two vehicles may need a larger reserve than someone living in a rental or senior community where maintenance is included.
The important thing is having some readily accessible money that doesn’t require selling investments or accumulating high-interest debt every time something unexpected happens.
Think of an emergency fund as financial breathing room.
Account for Inflation
A budget that works today may not work exactly the same way 10 or 20 years from now.
Inflation gradually reduces purchasing power.
Here’s a simple example.
Suppose your household currently spends $4,000 per month.
If those expenses increased by an average of 2.5% per year, maintaining roughly the same lifestyle would require approximately:
$5,120 per month after 10 years.
After 20 years, it would be approximately:
$6,550 per month.
Actual inflation will vary, and individual expenses won’t all rise at the same rate. But this example demonstrates why a retirement budget shouldn’t assume today’s prices will remain unchanged indefinitely.
Review your budget regularly and make adjustments as costs change.
Don’t Be So Frugal That You Stop Enjoying Retirement
There is another side to retirement budgeting that receives less attention: spending too little.
Some retirees become so concerned about running out of money that they hesitate to spend anything beyond necessities.
That can mean avoiding vacations, hobbies, restaurants, family experiences, or other activities they could reasonably afford.
Financial responsibility is important, but retirement savings were accumulated for a purpose.
Your budget should help you determine what you can comfortably spend—not simply tell you what you shouldn’t spend.
Consider creating a specific “enjoyment” category.
Maybe that’s $100 per month for hobbies.
Maybe it’s $300.
Maybe you set aside $4,000 annually for travel.
The appropriate amount depends on your financial situation, but intentionally including enjoyable spending can remove some of the guilt associated with using retirement savings.
Watch for Emotional Spending
Money isn’t purely mathematical.
Emotions can affect spending at every age.
Retirement may introduce lifestyle changes that make emotional spending more noticeable.
Boredom can encourage shopping.
Loneliness can lead to excessive spending on entertainment or gifts.
Stress can make financial decisions feel overwhelming.
You don’t need to eliminate spontaneous purchases. Simply become aware of your patterns.
Before making a significant unplanned purchase, consider waiting 24 or 48 hours.
Ask yourself:
Do I genuinely want this, or am I responding to how I’m feeling today?
That small pause can prevent many purchases you might later regret.
Review Housing Costs Carefully
Housing is often one of the largest retirement expenses.
Your housing situation deserves periodic review, even if you have no intention of moving.
Consider:
- Mortgage payments
- Property taxes
- Homeowners insurance
- HOA fees
- Utilities
- Maintenance
- Landscaping
- Major repairs
- Accessibility modifications
A paid-off home isn’t necessarily a free home.
Taxes, insurance, maintenance, and utilities continue.
For some retirees, staying in their current home makes financial and emotional sense.
Others may eventually benefit from downsizing, relocating, or moving into a community where some maintenance expenses are included.
There’s no universal right answer.
The goal is to understand the true cost of your housing choice.
Give Yourself Permission to Adjust
Your first retirement budget probably won’t be your final retirement budget.
That’s normal.
Your spending at age 67 may look very different from your spending at 77 or 87.
Early retirement might involve more travel and recreation.
Later retirement could involve less travel but greater healthcare or household assistance expenses.
Family circumstances can also change.
Instead of treating your budget as permanent, think of it as a living financial plan.
Review it periodically and ask:
- Has my income changed?
- Have my essential expenses increased?
- Am I spending more or less than expected?
- Are there expenses I no longer value?
- Do I have enough emergency savings?
- Has my healthcare situation changed?
- Are my withdrawals still appropriate?
Even a simple annual review can help keep your finances aligned with your life.
When Financial Stress Starts Affecting Your Well-Being
A retirement budget should create clarity—not constant fear.
Consider reassessing your approach if you find yourself:
- Constantly checking account balances
- Feeling guilty about ordinary purchases
- Avoiding affordable activities because you’re afraid to spend
- Losing sleep over money
- Making impulsive financial decisions
- Struggling to understand retirement withdrawals
- Frequently borrowing to cover regular expenses
Sometimes the problem is spending.
Sometimes the budget is unrealistic.
And sometimes uncertainty itself is creating anxiety.
A qualified financial professional may be able to help you understand your income, investments, withdrawal strategy, taxes, and long-term financial outlook.
Protect Yourself From Financial Scams
Budget sustainability isn’t only about how much you spend. It’s also about protecting what you’ve accumulated.
Be cautious whenever someone pressures you to:
- Transfer money immediately
- Buy gift cards
- Send cryptocurrency
- Provide passwords
- Share verification codes
- Give remote access to your computer
- Make an investment decision immediately
Legitimate financial decisions rarely require panic.
If someone contacts you unexpectedly about money, stop and independently verify who they are before taking action.
It can also be useful to discuss major financial decisions with a trusted family member, attorney, accountant, or financial professional.
Create a Simple Monthly Retirement Routine
Managing a retirement budget doesn’t need to become a full-time job.
Consider choosing one day each month as your financial check-in.
Spend 20 or 30 minutes reviewing:
- Income received
- Regular expenses
- Credit card balances
- Bank balances
- Upcoming large expenses
- Emergency savings
- Unusual transactions
Then ask:
Did my spending generally match my plan?
If yes, move on and enjoy the rest of your month.
If not, determine why.
One unusually expensive month doesn’t necessarily mean there’s a problem. Several consecutive months of overspending may indicate that your budget needs adjustment.
Think in Years, Not Just Months
Monthly budgeting is useful, but retirement is a long-term journey.
Consider creating an annual spending plan too.
For example, your normal monthly expenses might total $3,500, or $42,000 annually.
But perhaps you also expect:
- $3,000 for travel
- $1,500 for home repairs
- $1,000 for holiday gifts
- $1,500 for vehicle expenses
Your realistic annual spending isn’t $42,000.
It’s closer to $49,000.
That difference matters when determining how much income your retirement plan needs to support.
Related Guidance You May Find Helpful
Financial well-being is only one part of a satisfying retirement. You may also find these topics helpful:
- How to Stay Positive Through Aging Changes
- How to Build Meaning and Purpose in Retirement
- How to Strengthen Your Inner Confidence
- How to Prepare for Longevity and Future Needs
Together, financial preparation, health, relationships, and a sense of purpose can create a stronger foundation for retirement.
Final Thoughts
A sustainable retirement budget isn’t about controlling every dollar.
It’s about understanding where your money comes from, where it goes, and whether your spending can comfortably continue over time.
Start with your reliable income.
Identify your essential expenses.
Make room for enjoyable spending.
Prepare for irregular costs.
Maintain an emergency buffer.
Account for healthcare and inflation.
Then revisit your plan as your life changes.
Most importantly, remember why you’re budgeting in the first place.
You spent decades building the resources that support your retirement. Financial security matters—but so does enjoying the life those resources were designed to provide.
A good retirement budget should give you permission to do both.
Disclaimer: This article is for general educational purposes only and does not constitute financial, investment, tax, legal, or insurance advice. Retirement needs vary considerably by individual. Consider consulting an appropriately qualified professional regarding your personal financial circumstances.