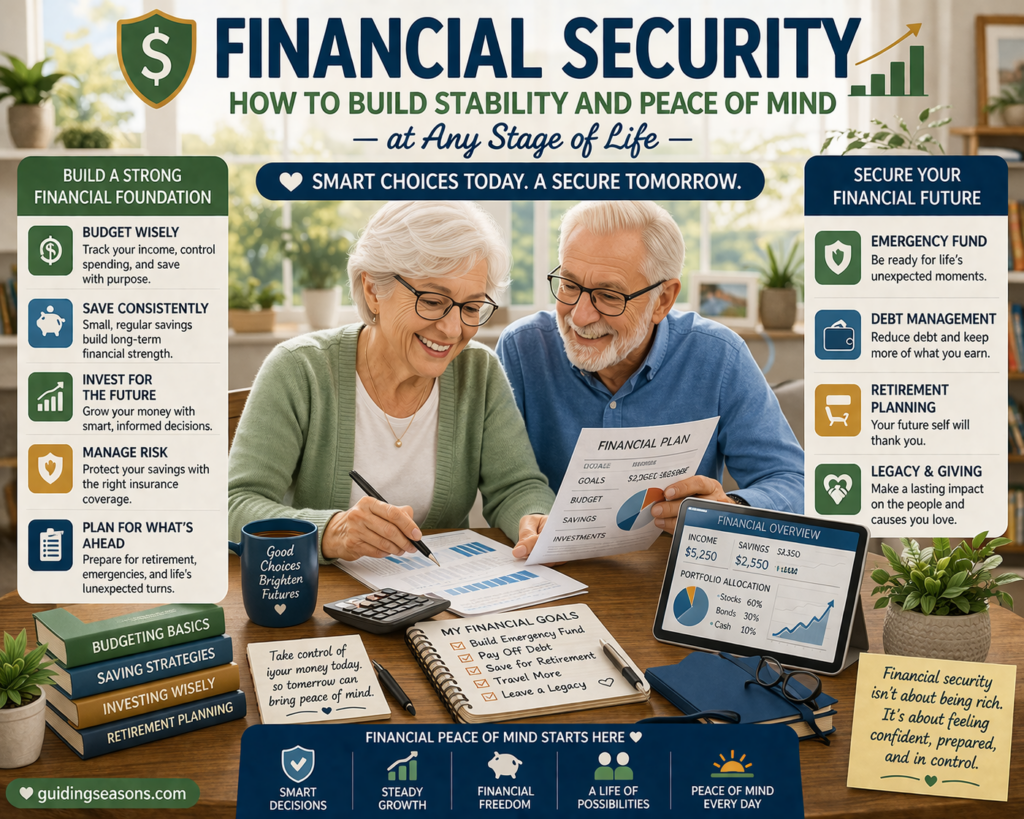
Financial security isn’t simply about how much money you have. It’s about having confidence, control, and resilience in your financial life.
When your finances are reasonably stable, everyday decisions become easier. An unexpected repair is less frightening. Monthly bills feel more manageable. Planning for retirement, healthcare, housing, or family needs becomes less overwhelming.
Financial security can look different depending on your stage of life. Someone in their 40s may be focused on reducing debt and increasing retirement savings, while someone who has already retired may care more about controlling expenses, protecting savings, and making a fixed income last.
The goal is not to achieve financial perfection. It is to build a practical system that helps you remain prepared, independent, and confident even when circumstances change.
This guide covers the major areas of financial security, from budgeting and emergency savings to retirement income, insurance, debt, fraud protection, estate planning, and organizing your financial life.
What Financial Security Really Means
Financial security means having enough stability and preparation to meet your needs without constantly worrying about money.
For most people, that includes being able to:
- Pay essential monthly expenses
- Manage bills consistently
- Handle reasonable unexpected expenses
- Keep debt under control
- Maintain appropriate insurance coverage
- Save for future needs
- Protect money and personal information
- Make informed financial decisions
- Prepare for retirement and later-life expenses
- Maintain as much financial independence as possible
You do not necessarily need a large income or substantial wealth to improve your financial security.
What matters is how well your available resources are managed.
Someone with a modest income, manageable expenses, limited debt, emergency savings, and a clear financial plan may feel considerably more secure than someone earning much more but carrying excessive expenses and debt.
Financial security is ultimately about creating margin between what you have and what you need.
Why Financial Stability Matters More Than You Think
Money problems rarely stay confined to a bank account.
Financial uncertainty can influence your decisions about housing, healthcare, relationships, retirement, transportation, travel, and even how comfortable you feel helping family members.
When finances are unstable, people may experience:
- Persistent worry about bills
- Difficulty planning ahead
- Fear of unexpected expenses
- Reliance on credit cards
- Delayed healthcare or home repairs
- Uncertainty about retirement
- Difficulty making major life decisions
Financial stability does not eliminate every problem. Unexpected events will still happen.
What changes is your ability to respond.
Instead of every surprise becoming a crisis, you have resources, habits, and plans that can help you adapt.
Start by Understanding Where You Stand
Before trying to improve your finances, develop a clear picture of your current situation.
You do not need complicated software or spreadsheets. Start with four basic questions:
- How much money comes in each month?
- How much goes out?
- What do you own?
- What do you owe?
List your regular sources of income, such as:
- Employment income
- Social Security
- Pension payments
- Retirement account withdrawals
- Investment income
- Rental income
- Part-time work
- Other recurring income
Then list your major expenses.
Include both fixed and variable expenses such as housing, utilities, insurance, groceries, transportation, healthcare, subscriptions, debt payments, entertainment, and personal spending.
If keeping track of purchases feels overwhelming, How to Track Spending Easily as a Senior explains ways to make the process simpler.
The purpose isn’t to account for every penny forever. It is to understand the overall pattern of your financial life.
Build a Budget That Reflects Real Life
A useful budget should help you make decisions, not make you feel restricted.
Begin by separating expenses into three general categories:
Essential expenses
These are costs you generally cannot avoid:
- Housing
- Utilities
- Groceries
- Healthcare
- Insurance
- Transportation
- Minimum debt payments
Flexible expenses
These are necessary or worthwhile expenses that can often be adjusted:
- Dining out
- Entertainment
- Clothing
- Travel
- Gifts
- Hobbies
- Subscription services
Future expenses
These are expenses that may not occur every month but should still be planned for:
- Vehicle repairs
- Home maintenance
- Insurance deductibles
- Property taxes
- Holiday spending
- Medical expenses
- Travel
- Appliance replacement
Planning for irregular expenses is important because many supposed “emergencies” are actually predictable expenses that simply do not occur every month.
Reduce Expenses Without Making Life Miserable
Cutting expenses does not mean eliminating everything enjoyable.
The goal is to identify spending that provides little value and redirect that money toward things that matter more.
Start with recurring expenses because small monthly charges can quietly become significant annual costs.
Review:
- Streaming services
- Memberships
- Phone plans
- Internet plans
- Insurance premiums
- Banking fees
- Delivery subscriptions
- Automatic renewals
After retirement, reviewing expenses can become especially valuable because income may be less flexible than it was during your working years.
Our guide on How to Reduce Monthly Expenses After Retirement provides additional strategies for lowering ongoing costs without unnecessarily reducing quality of life.
Simplify Your Financial Life
Financial complexity can create unnecessary stress.
If you have numerous accounts, subscriptions, bills, cards, and payment dates, managing everything can become increasingly difficult.
Simplification might include:
- Consolidating unnecessary accounts where appropriate
- Canceling unused subscriptions
- Automating predictable bills
- Using a consistent bill-paying schedule
- Reducing unnecessary credit cards
- Keeping financial records organized
- Limiting impulse purchases
A simpler system is easier to understand and maintain.
If you prefer a more intentional approach to spending and possessions, read How to Build a Minimalist Financial Lifestyle.
Build an Emergency Safety Net
One of the strongest foundations of financial security is having money available when something unexpected happens.
Emergencies might include:
- Major vehicle repairs
- Home repairs
- Medical expenses
- Emergency travel
- Temporary loss of income
- Insurance deductibles
- Unexpected family needs
Without savings, these expenses may end up on credit cards or other forms of debt.
You do not have to build a large emergency fund immediately.
A smaller initial goal can still provide meaningful protection. Once you reach it, continue building gradually.
If your income is limited, How to Build a Safety Net on a Fixed Income offers strategies for making progress without requiring large monthly contributions.
You can also review How to Prepare for Financial Emergencies for a broader approach to preparing for unexpected financial events.
Make Spending More Intentional
Financial stability depends not only on saving money but also on making better decisions about how you spend it.
Before making a significant purchase, consider:
- Do I actually need this?
- Can I comfortably afford it?
- Is there a lower-cost alternative?
- Will I still value it several months from now?
- Am I buying because of pressure or emotion?
- What will the total cost of ownership be?
A lower purchase price does not always mean something is cheaper in the long run. Maintenance, financing, insurance, subscriptions, and replacement costs can all matter.
If you are managing a limited retirement budget, How to Make Smart Purchases on a Fixed Income provides a practical framework for evaluating purchases.
Manage Debt Before It Controls Your Budget
Debt can significantly reduce financial flexibility.
Monthly payments consume income that could otherwise go toward savings, healthcare, travel, home maintenance, or everyday living.
Start by listing each debt along with its:
- Balance
- Interest rate
- Minimum payment
- Payment date
High-interest debt often deserves particular attention because interest can make balances increasingly difficult to repay.
Depending on your circumstances, possible strategies include:
- Paying more than the minimum when affordable
- Prioritizing high-interest balances
- Avoiding new unnecessary debt
- Contacting creditors when payments become difficult
- Seeking reputable financial or credit counseling when needed
Older adults facing debt have different considerations than younger borrowers because retirement income may be relatively fixed. How to Manage Debt Later in Life explores those issues in more detail.
Plan Carefully for Retirement Income
Retirement changes the way many people think about money.
Instead of primarily accumulating savings, you may begin relying on several different sources of income.
These might include:
- Social Security
- Pension payments
- Traditional retirement accounts
- Roth accounts
- Investment income
- Annuities
- Rental income
- Part-time employment
Understanding how these income sources work together can help you create a more predictable retirement budget.
For people receiving both benefits, How to Combine Pensions and Social Security provides a useful starting point.
Retirement security also requires looking beyond monthly income.
Consider future expenses involving:
- Healthcare
- Housing
- Inflation
- Transportation
- Home maintenance
- Long-term care
- Insurance
- Taxes
- Family support
If you are already retired, How to Increase Financial Stability After Retiring explores ways to strengthen your financial position during retirement.
Avoid Common Retirement Money Mistakes
Retirement can last decades, which means relatively small financial decisions may have long-term consequences.
Common mistakes include:
- Increasing spending too quickly after retiring
- Underestimating healthcare costs
- Carrying unnecessary high-interest debt
- Ignoring inflation
- Making large withdrawals without considering future needs
- Failing to review insurance
- Supporting family beyond what your finances can reasonably handle
- Falling for questionable investment opportunities
It is also important not to make major financial decisions simply because someone creates a sense of urgency.
Before moving retirement savings, purchasing a complicated financial product, or making a large commitment, take time to understand what you are agreeing to.
For more examples, see How to Avoid Common Money Mistakes in Retirement.
Understand Your Housing and Mortgage Options
Housing is often one of the largest components of a household budget.
Later in life, homeowners may consider whether to:
- Remain in their current home
- Pay off a mortgage
- Refinance
- Downsize
- Relocate
- Access home equity
- Consider specialized mortgage products
Each choice can affect monthly cash flow, available savings, taxes, insurance, maintenance costs, and estate plans.
There is rarely one housing strategy that works for everyone.
Before making a major decision involving your home, understand the costs, risks, and long-term consequences.
How to Understand Senior Mortgage Options provides an overview of mortgage considerations for older homeowners.
Review Insurance as Your Life Changes
Insurance is another important part of financial security because it transfers certain financial risks that could otherwise be difficult to absorb.
Depending on your circumstances, coverage may include:
- Health insurance
- Medicare-related coverage
- Homeowners or renters insurance
- Auto insurance
- Life insurance
- Long-term care coverage
- Other supplemental coverage
Insurance needs can change over time.
A policy that made sense when you were working, raising children, or paying a mortgage may not serve the same purpose later.
Rather than automatically renewing every policy, periodically review what you have, what it covers, and what it costs.
How to Compare Insurance Plans Easily explains factors to consider when comparing coverage.
Understand Medicare Supplement Options
Healthcare expenses can become a significant part of retirement planning.
Original Medicare does not cover every healthcare expense. Some beneficiaries purchase Medicare Supplement Insurance, commonly called Medigap, to help cover certain out-of-pocket costs.
Before choosing coverage, understand:
- What Original Medicare covers
- What the supplemental policy covers
- Premium costs
- Eligibility requirements
- How plans differ
- Whether your existing coverage overlaps
Because Medicare rules and plan availability can change, verify important decisions using current official information.
Our introductory guide, Understanding Medicare Supplement Plans, explains the basic concepts and terminology.
Consider Whether Life Insurance Still Fits Your Needs
Life insurance can serve several purposes, including providing financial support for surviving family members or helping address certain final expenses.
But insurance needs change.
Later in life, questions may include:
- Does anyone still depend on my income?
- Do I have outstanding debts?
- What would happen financially if I died?
- Do I already have sufficient savings or other assets?
- What are the policy premiums?
- Is the coverage still appropriate?
Avoid purchasing a policy simply because it is marketed specifically toward older adults.
Understand the benefits, exclusions, premiums, and limitations before committing.
Understanding Life Insurance for Seniors covers these considerations in greater detail.
Protect Yourself From Identity Theft
Financial security also means protecting the money and information you already have.
Identity theft can involve:
- Stolen credit card information
- Unauthorized accounts
- Fraudulent loans
- Tax-related fraud
- Medical identity theft
- Account takeovers
Simple precautions can reduce risk.
Use strong, unique passwords, enable multifactor authentication when available, review financial statements, protect sensitive documents, and be cautious about sharing personal information.
For additional steps, read How to Protect Your Identity From Theft.
Learn to Recognize Financial Scams
Financial scams can affect anyone, but some criminals deliberately target older adults because they may have accumulated retirement savings, home equity, or reliable monthly income.
Warning signs can include:
- Unexpected requests for money
- Pressure to act immediately
- Promises of guaranteed investment returns
- Requests for passwords or verification codes
- Demands for unusual payment methods
- Threats involving taxes or government agencies
- Someone claiming a relative is in an emergency
- Unsolicited investment opportunities
A useful rule is simple: urgency should make you more cautious, not less cautious.
When someone pressures you to make an immediate financial decision, stop and independently verify the situation.
Read How to Avoid Financial Scams Targeting Seniors for more examples and prevention strategies.
You should also be cautious with loans, investments, insurance products, and other offers that contain excessive fees or unfavorable terms. How to Avoid Predatory Financial Offers explains common warning signs.
Know When to Seek Professional Financial Advice
Some financial decisions can be handled independently. Others may benefit from professional assistance.
You might consider seeking help when dealing with:
- Retirement planning
- Investment decisions
- Complex tax situations
- Estate planning
- Insurance decisions
- Significant debt
- Major inheritance
- Selling a home
- Long-term care planning
However, the title “financial advisor” alone should not automatically establish trust.
Before working with someone, understand:
- Their qualifications
- How they are compensated
- What services they provide
- Whether they have conflicts of interest
- What fees you will pay
How to Find Legitimate Financial Advice explains how to evaluate financial professionals more carefully.
Organize Important Financial Documents
Financial organization becomes increasingly valuable as your finances become more complex.
Important documents may include:
- Bank account information
- Insurance policies
- Tax records
- Retirement account information
- Pension documents
- Social Security records
- Property documents
- Mortgage information
- Estate documents
- Contact information for financial professionals
Keep important records somewhere secure and make sure an appropriate trusted person knows how necessary information can be accessed in an emergency.
Avoid leaving passwords or sensitive financial information somewhere easily accessible.
For a more complete system, see How to Organize Important Financial Documents.
Make Estate Planning Part of Financial Security
Estate planning is not only for wealthy families.
At its most basic level, estate planning helps clarify what should happen to your property and responsibilities if you die or become unable to make decisions yourself.
Depending on your situation, planning may involve:
- A will
- Beneficiary designations
- Powers of attorney
- Healthcare directives
- Trusts
- Property ownership arrangements
Laws vary by location and personal circumstances, so important estate decisions may require qualified legal assistance.
Estate Planning Basics Seniors Should Know provides an introduction to the major concepts.
Managing Money After Losing a Spouse
Losing a spouse can create both emotional and financial challenges.
A surviving spouse may suddenly need to manage accounts, insurance, household expenses, taxes, Social Security decisions, property, and estate matters that were previously handled together.
When possible, avoid feeling pressured into making major irreversible financial decisions immediately.
Start by identifying:
- Current income
- Essential monthly expenses
- Available accounts
- Insurance policies
- Outstanding debts
- Important deadlines
- Beneficiary information
- Professional contacts
Our guide on How to Manage Money as a Widowed Senior provides a more focused approach to navigating this transition.
Create a System for Managing Bills
Missing bills can lead to late fees, service interruptions, interest charges, and unnecessary stress.
A simple bill-management system might involve:
- Listing recurring bills.
- Recording their due dates.
- Choosing one or two days each month to review finances.
- Automating predictable payments where appropriate.
- Reviewing statements for errors or unexpected charges.
Automation can be useful, but do not completely stop reviewing your accounts. Automatic payments can continue even when a subscription is no longer needed or a charge is incorrect.
How to Manage Bills Without Stress offers additional ways to create an easier routine.
Small Financial Changes Can Have a Large Effect
Financial progress is often less dramatic than people expect.
It usually comes from repeating small, useful behaviors.
For example:
- Reviewing your accounts once a week
- Canceling one unused subscription
- Saving a small amount every payday
- Paying slightly more toward debt
- Comparing insurance periodically
- Planning large purchases before making them
- Reviewing your retirement plan annually
- Keeping important documents organized
A $20 improvement may not feel significant today.
But repeated across many categories and many months, small improvements can gradually create more room in your budget.
Consistency compounds.
Financial Habits Worth Reviewing Every Month
A simple monthly financial review can help you stay aware without thinking about money every day.
Review:
- Income received
- Major expenses
- Account balances
- Credit card balances
- Upcoming bills
- Savings progress
- Unusual transactions
- Expected large expenses
Then ask yourself:
Is my financial position improving, staying roughly the same, or getting worse?
If it is getting worse, identify why.
Perhaps expenses increased. Maybe an unexpected cost occurred. Perhaps debt is growing.
Recognizing a problem early usually gives you more options for addressing it.
Financial Tasks Worth Reviewing Every Year
Some financial decisions do not require monthly attention.
Once or twice a year, consider reviewing:
- Insurance coverage
- Retirement savings
- Beneficiaries
- Estate documents
- Credit reports
- Subscription services
- Financial goals
- Housing costs
- Healthcare expenses
- Tax planning
- Emergency savings
Major life changes should also trigger a financial review.
Examples include:
- Marriage
- Divorce
- Death of a spouse
- Retirement
- Moving
- Buying or selling a home
- Major health changes
- Receiving an inheritance
- Starting or leaving a job
Your financial plan should evolve as your life changes.
Mistakes That Can Slow Financial Progress
Building security is partly about knowing what to do and partly about avoiding behaviors that repeatedly undermine progress.
Watch for:
- Ignoring financial problems
- Trying to fix everything at once
- Carrying unnecessary high-interest debt
- Spending without tracking
- Making emotional investment decisions
- Falling for “guaranteed” financial opportunities
- Buying products you do not understand
- Neglecting insurance
- Failing to maintain emergency savings
- Comparing your financial situation constantly with others
Financial progress is personal.
Someone else may have a larger home, newer vehicle, or more expensive lifestyle while also carrying substantial debt.
Focus on strengthening your own financial position.
A Simple Financial Security Framework
If all of this feels like a lot, reduce it to a simple sequence.
Step 1: Understand
Know what you earn, spend, own, and owe.
Step 2: Stabilize
Make sure essential expenses are consistently covered.
Step 3: Protect
Build emergency savings and maintain appropriate insurance.
Step 4: Reduce
Work on expensive debt and unnecessary recurring expenses.
Step 5: Prepare
Plan for retirement, healthcare, housing, and other future expenses.
Step 6: Organize
Keep important financial and estate information accessible and secure.
Step 7: Review
Revisit your financial plan periodically as your circumstances change.
You do not have to accomplish all seven steps at once.
Improving one area at a time can gradually transform your financial situation.
How Financial Security Improves Everyday Life
The value of financial security goes far beyond a bank balance.
Greater stability can provide:
- More freedom when making decisions
- Less anxiety about unexpected expenses
- Greater confidence about retirement
- More flexibility during emergencies
- Reduced dependence on debt
- Better ability to help family when appropriate
- More control over housing and lifestyle decisions
Most importantly, financial security creates options.
When your finances are organized and resilient, you are better positioned to decide how you want to live rather than allowing every decision to be dictated by immediate financial pressure.
Continue Building Your Financial Security
Financial stability is made up of many smaller skills. Depending on where you are today, one area may deserve attention before the others.
If monthly expenses are the problem, begin by tracking spending and reducing recurring costs.
If unexpected expenses continually push you toward credit cards, concentrate on building a safety net.
If retirement is approaching, focus on income, healthcare, housing, insurance, and long-term expenses.
If your finances are already reasonably stable, turn your attention toward protection, organization, estate planning, and long-term resilience.
For a broader look at maintaining that progress over time, read How to Build Long-Term Financial Confidence.
Final Thoughts
Financial security is rarely created by one brilliant investment, one perfect budget, or one major financial decision.
It is usually built quietly through hundreds of smaller decisions.
You understand where your money goes.
You spend less than you can afford when possible.
You prepare for emergencies.
You manage debt carefully.
You protect yourself from unnecessary risks.
You plan ahead.
And when your circumstances change, you adjust.
You do not need to solve your entire financial future today.
Start with the area creating the most pressure, make one practical improvement, and continue from there.
Over time, those decisions can create something far more valuable than simply having more money: greater stability, independence, confidence, and peace of mind.